By The Low Interest
14 Sep, 2026
Zero Processing Fee Personal Loans: What's the Real Catch?
home > loans > personal loan > zero processing fee
Zero processing fee is one of the most common hooks in personal loan advertising, and one of the most misunderstood. It sounds like money saved outright, but a loan's real cost is almost never determined by a single fee.
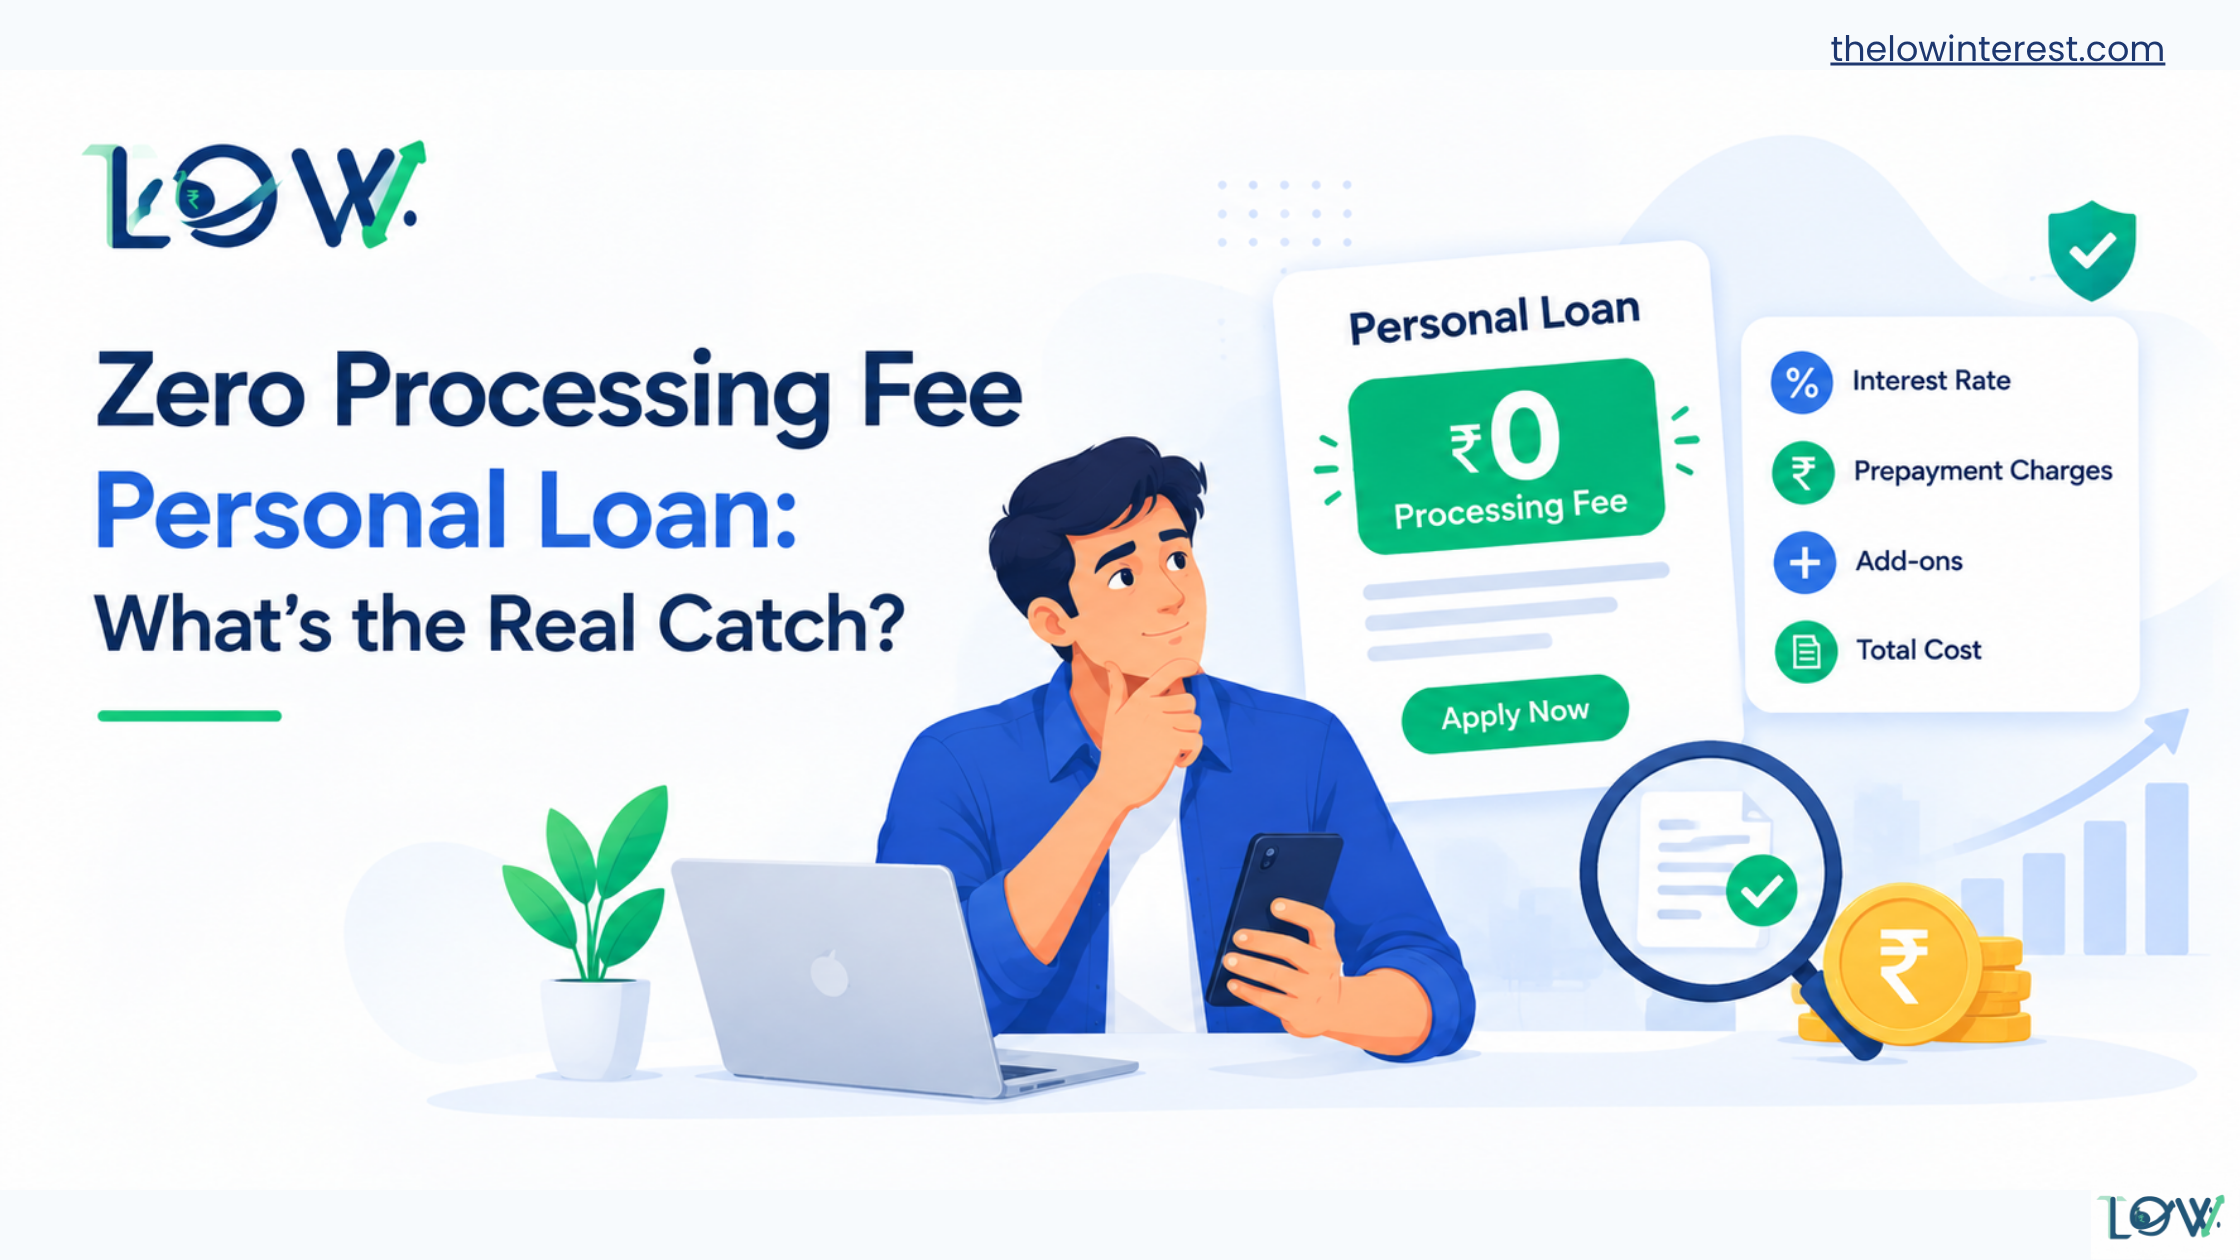
A zero processing fee personal loan waives the upfront charge lenders normally deduct from your disbursed amount. It's often a genuine saving, but some lenders offset it with a marginally higher interest rate, stricter eligibility, or bundled add-ons — so it's worth comparing the total cost, not just the headline fee. |
What Is a Processing Fee In Loans?
A processing fee is a one-time charge lenders collect to cover credit checks, document verification, and administrative work. It's typically a percentage of your loan amount, in the low single digits, and deducted from your disbursed amount rather than billed separately.
Why Would a Lender Waive It?
attracting new borrowers, especially among digital-first NBFCs competing for market share
festive or year-end offers designed to boost loan volume
existing customers with a strong repayment history sometimes qualify automatically
waived as part of a broader relationship, such as a salary account or existing credit card
None of these reasons is inherently suspicious — but none of them guarantees the loan is your cheapest overall option either.
Where the Catch Sometimes Hides
A slightly higher interest rate. Some lenders offset a waived fee with a marginally higher rate — the total cost over the tenure can end up equal to, or higher than, a loan with a small fee but a lower rate.
Prepayment or foreclosure charges. Check whether the zero-fee loan carries higher penalties for closing early — this is a common place lenders recover margin.
Mandatory add-ons. Some zero-fee offers bundle in mandatory insurance or add-on products, raising your effective cost even though the headline fee is genuinely zero.
Eligibility restrictions. Zero-fee offers are sometimes limited to specific score bands, loan amounts, or existing customers — read the fine print rather than assuming it applies universally.
How to Actually Compare Loan Offers
Don't compare on processing fee or interest rate alone. Calculate the effective total cost across the full tenure, factoring in:
What to Check, and Why It Matters
What to Check | Why It Matters |
|---|
Interest rate | The largest cost component over the loan's life | Processing fee | A one-time cost that affects your disbursed amount | Prepayment charges | Matters most if you plan to close the loan early | Mandatory add-ons | Can silently raise the total cost | Tenure flexibility | Affects total interest paid over time
|
|
When a Zero-Fee Loan Is a Genuinely Good Deal
It's a strong offer when the interest rate matches or beats the lender's standard rate, there are no unusual prepayment penalties, and no mandatory bundled products are attached. In that case, you're simply keeping the fee with no hidden trade-off.
Frequently Asked Questions
Is a zero processing fee loan always cheaper overall?
Not necessarily. Always compare the full interest rate and any prepayment charges, since some lenders offset a waived fee elsewhere in the structure.
Do zero-fee loans have stricter eligibility?
Sometimes — these offers can be limited to specific score ranges, loan amounts, or existing customers, so check the eligibility details first.
Can I negotiate a processing fee waiver?
In some cases, yes, particularly with an existing strong relationship or a high CIBIL score — it's reasonable to ask directly during the application.
Are there hidden charges in zero-fee loans?
Not always, but it's worth explicitly checking for prepayment penalties, mandatory insurance, or a marginally higher rate before signing.
How do I calculate a loan's true cost?
Add up total interest over the tenure, any processing fee, and possible prepayment charges — comparing this total across lenders gives a far clearer picture than any single fee.
Should I always pick the zero-fee option over one with a small fee?
Not automatically — compare the effective total cost first; a loan with a small fee but a meaningfully lower rate can work out cheaper overall.
Key Takeaways
- Processing fee is only one component of a loan's real cost.
- Check the interest rate, prepayment charges, and any mandatory add-ons before deciding.
- Zero-fee offers are often genuine promotions, not necessarily a trap — but they still need comparison.
- Calculate the effective total cost across the full tenure, not just the upfront fee.
Conclusion
A zero processing fee is a genuine saving when everything else about the loan is comparable — but it isn't automatically the cheapest option available. The only reliable way to know is to compare the full cost structure, not just the headline fee.
Before you apply, compare the full cost — interest rate, fees, and prepayment terms together — to make sure "zero processing fee" actually means the best deal for you.
Rates, fees, and eligibility criteria vary by lender and change over time. Confirm current terms directly with your lender before applying.
Reviewed by TheLowInterest.com's lending editorial team | Last updated: Sep 2026